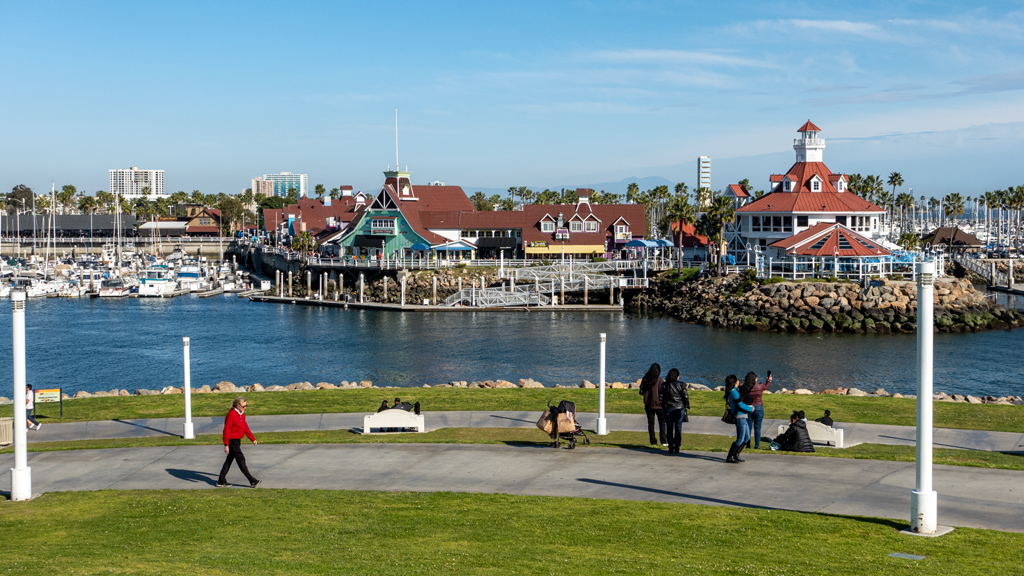
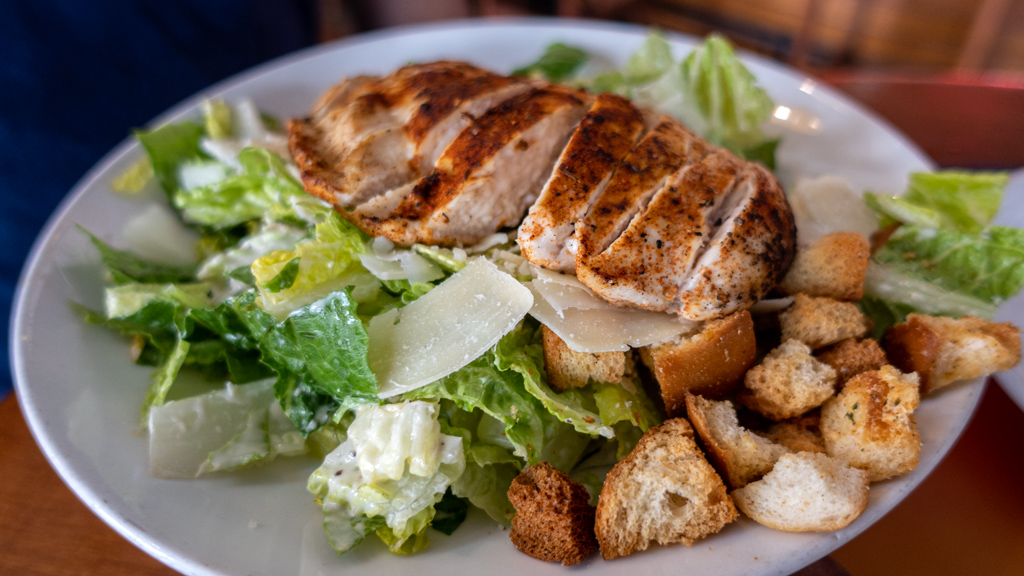Photo dump from early 2023

After spending the winter setting up a temporary home base at the Tempo headquarters in Long Beach, California, the time has come for me to continue to my next destination.

I spent more time there than I usually do because we had some behind-the-scenes stuff happening on the logistical and operational side of the company that I had to tend to, but that also meant that I didn’t have a chance to do as much exploring as I wanted to… not that the amount I wanted to was that much to begin with anyway, though.

I noticed that this has been a recurring theme every time I visit California—the traffic is so paralyzingly bad, and for some reason, I generally just feel less motivated than I usually am, so I end up just staying indoors a lot.

This means that I didn’t really do much that would warrant their own dedicated blog posts like I regularly did when I was out non-stop road tripping, but I do still have a smorgasbord of photographs, so I wanted to share a handful of them here.

This is my friend’s greyhound Majima. He is very lanky, awkward, and clearly ecstatic to be a part of this picture.
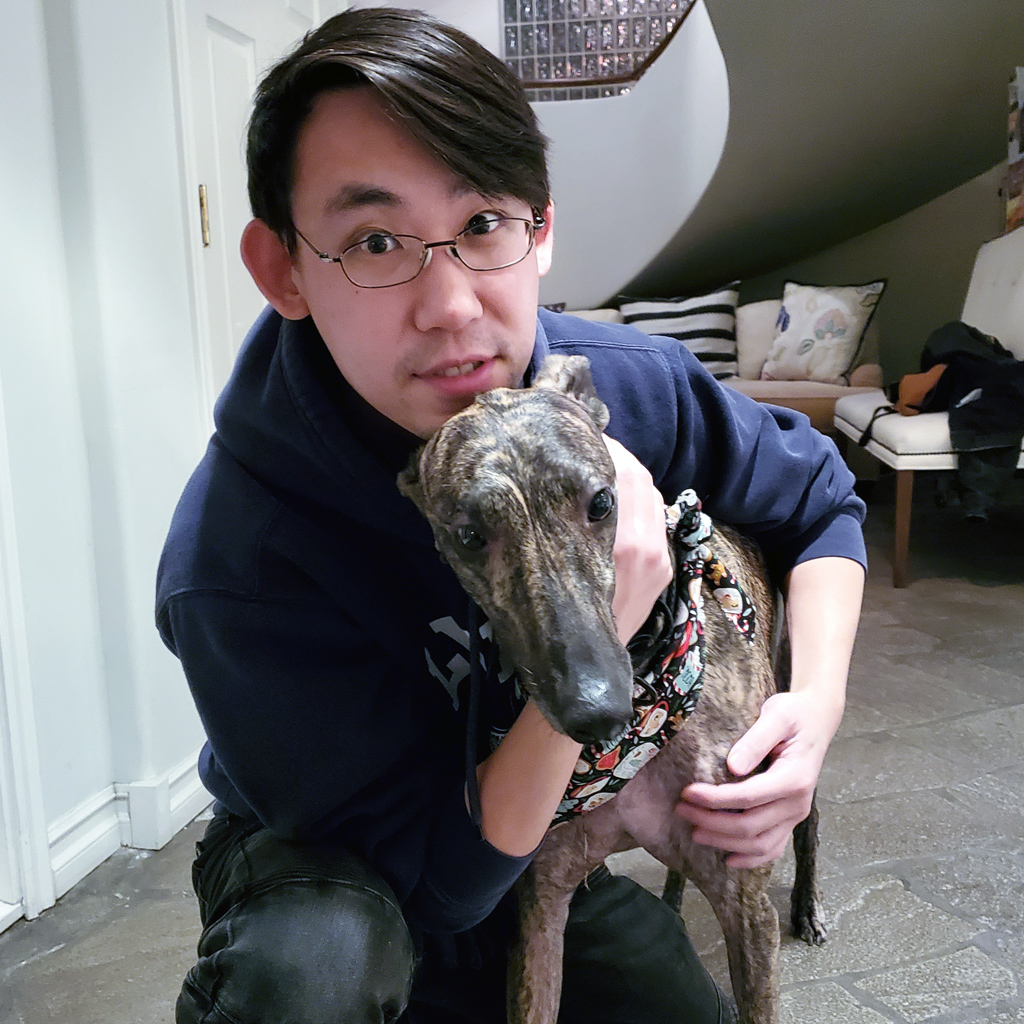
Adam Parkzer hugging a greyhound

The CEO of Tempo, one of our Producers, and I all share similar birthdays within the span of a few days, so near the end of January, we celebrated by going to some nice restaurants. One of them was the Naples Rib Company in Long Beach, California.

I’m still eating a diet low in saturated fat for heart health, so I ordered some swordfish instead of barbecue ribs. The swordfish filet was tender and juicy, the flavor was exactly what you’d expect from nicely-cooked swordfish, the sauce was perfectly complementary without being too overwhelming, and the sides added richness and texture to the main entrée.
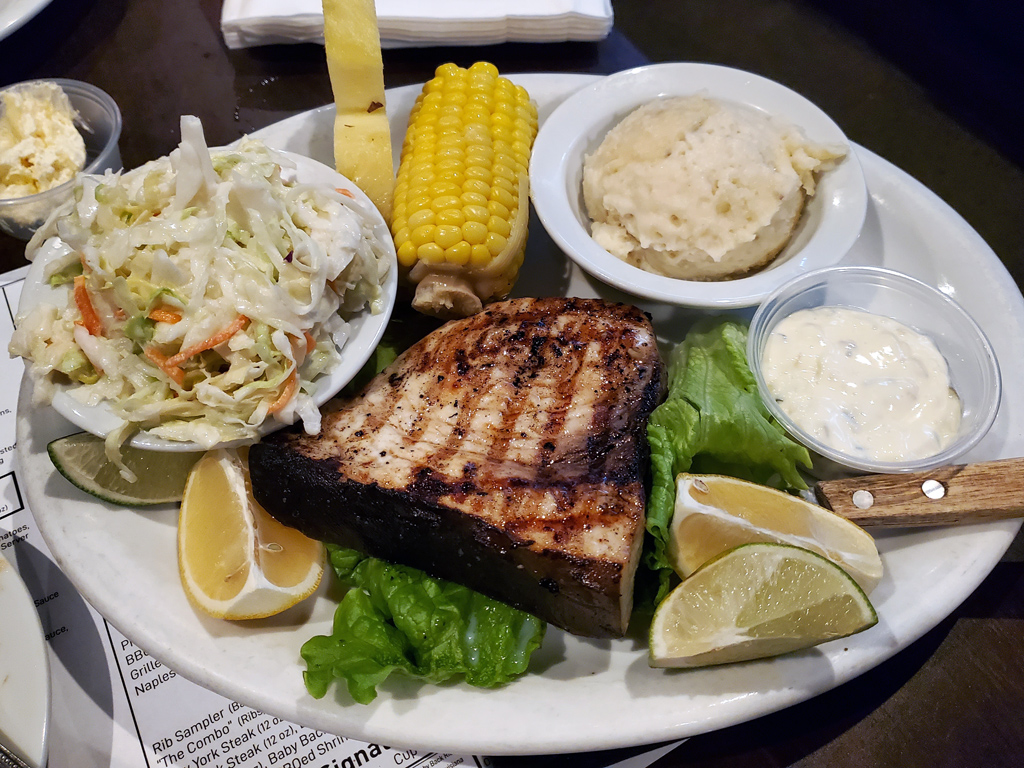
While stationed at the residential quarters of Tempo’s facility, considering that I wasn’t personally paying for rent or otherwise being charged a fee like I do with hotels or other forms of lodging, I was more willing to go on air travel trips.

One convenient thing about the location of the company headquarters is that it is in close proximity to both Long Beach Airport (LGB) in Long Beach, California and John Wayne Airport (SNA) in Santa Ana, Orange County, California. This means that I can fly out of much smaller airports, as opposed to going all the way over to Los Angeles International Airport (LAX).

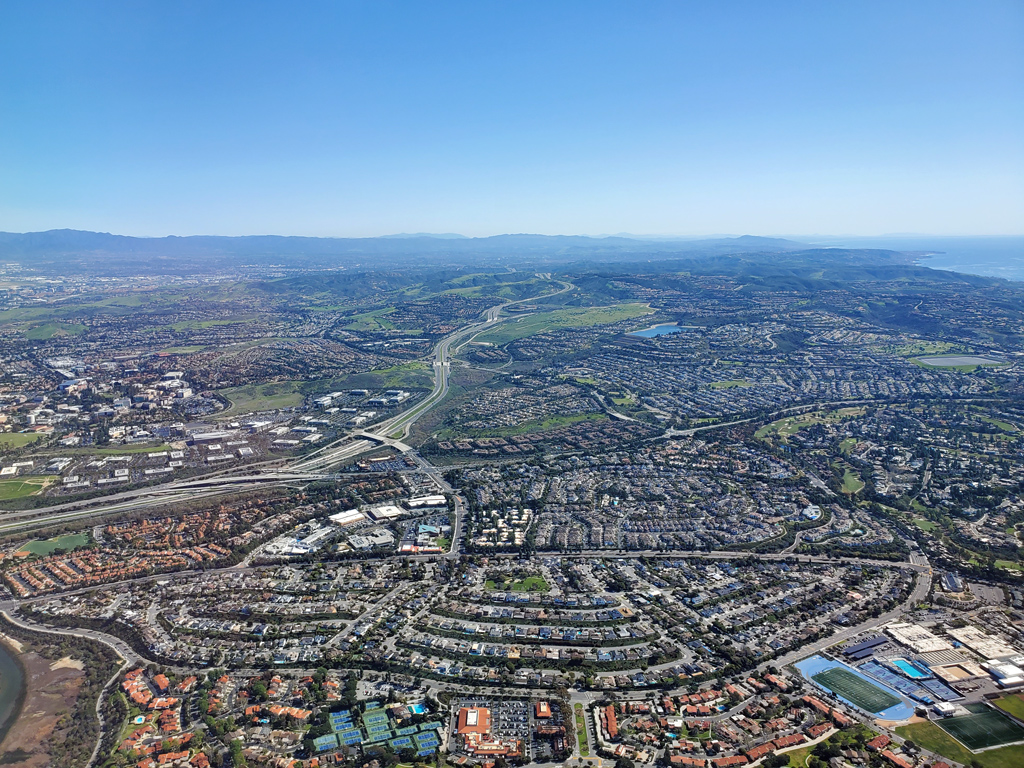
Here’s a photo of the Orange County suburbs:
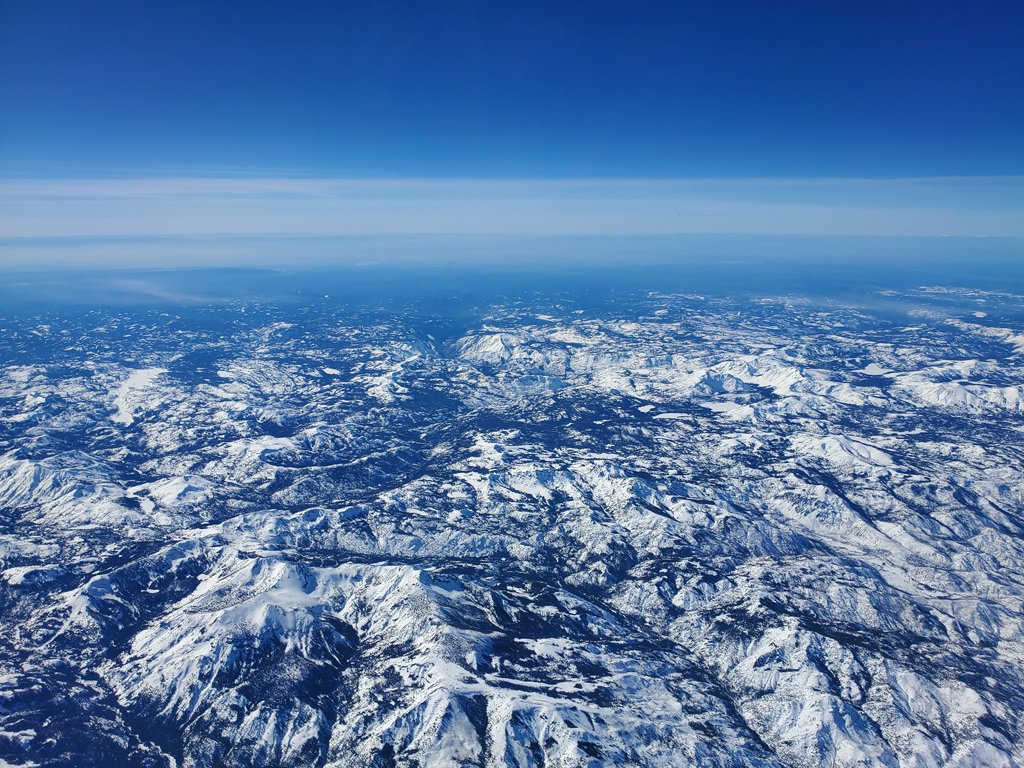
… as well as the snowy mountains in northern California up by Lake Tahoe:
Air travel hasn’t been the best experience shortly after the initial surge of quarantine mandates during the pandemic, as most airlines decided to roll over everyone’s elite status, so it wasn’t special anymore to be a loyalty member—this meant that the upgrade list was oversaturated, so it was very rare to get free upgrades to first class if you weren’t one of the highest elite tiers.

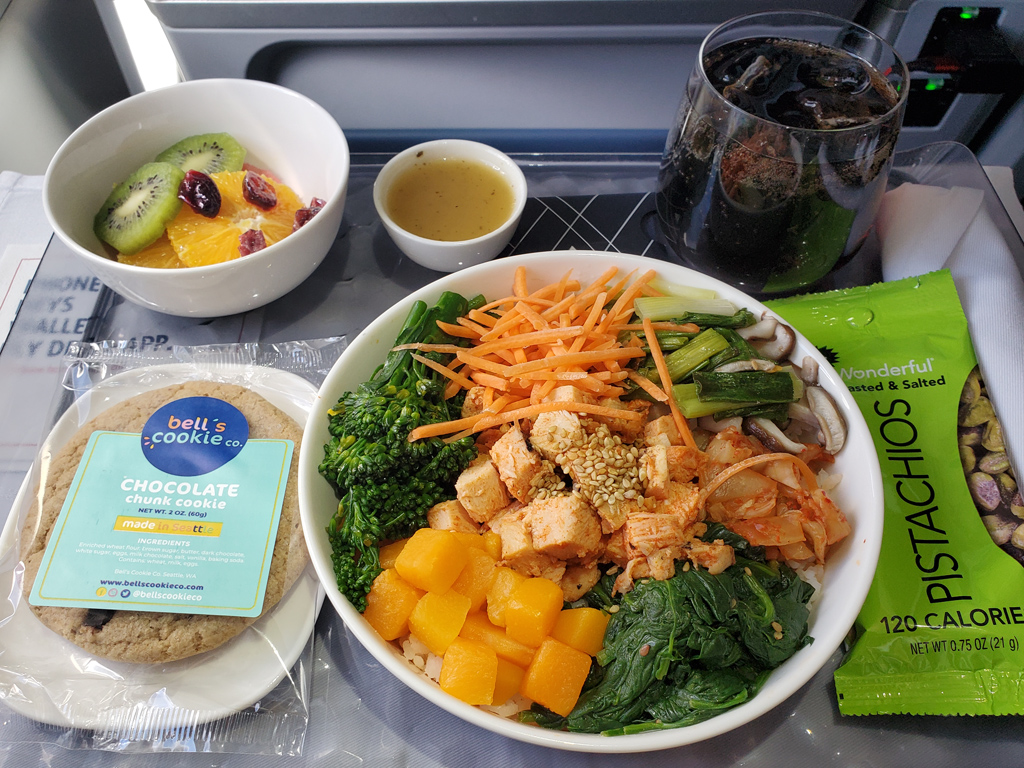
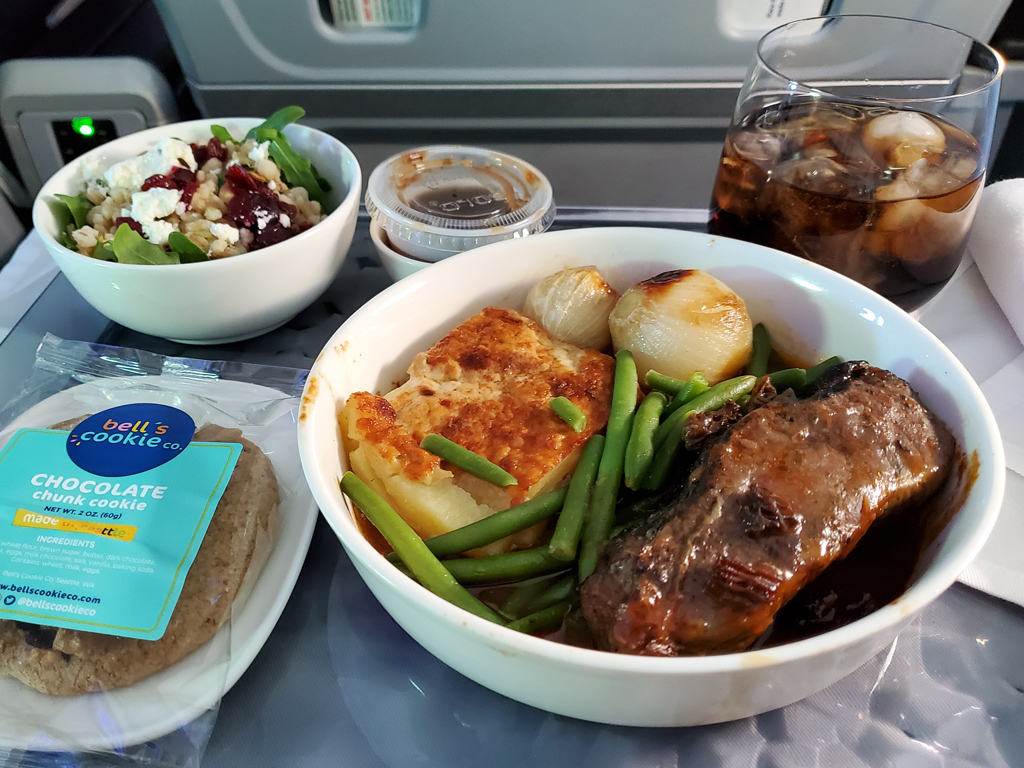
However, in a “nature is healing” moment, I managed to be able to fly first class again on Delta Air Lines. Even better, regular meal service has been re­stored (as opposed to the “deluxe snack boxes” that they switched over to during the pandemic, where everything was pre-packaged to avoid physical con­tact by the flight attendants with the food). It wasn’t the best food ever, but definitely better than just having 8 different kinds of chips and crackers.
I also squeezed in a Las Vegas trip as well, for the usual—to check my mail, get a haircut, meet up with friends, and take care of some other errands. My hotel of choice for this trip was the ENGLiSH Hotel, part of the Marriott Tribute Portfolio, located in downtown Las Vegas on Main Street in the Arts District.
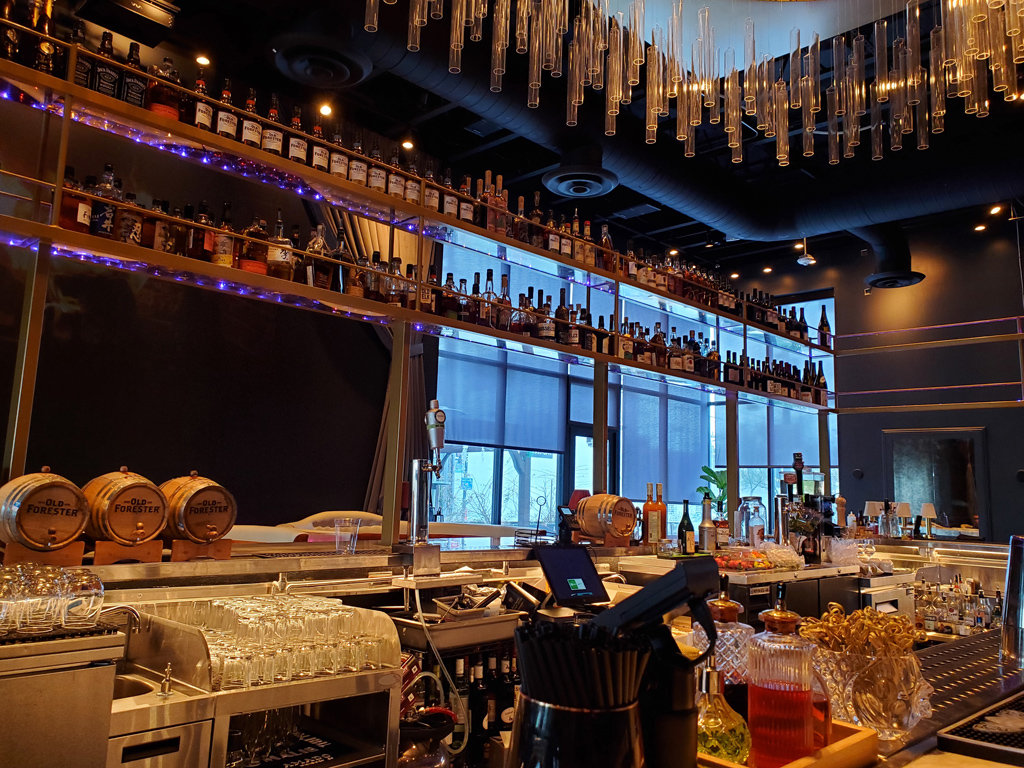
The hotel was pleasant, though I wasn’t a fan of the parking situation—the hotel’s lot is tiny, so I ended up having to street park… and downtown Las Vegas doesn’t exactly have the best reputation for being the most secure area in the Valley. Luckily, nothing happened to my truck.

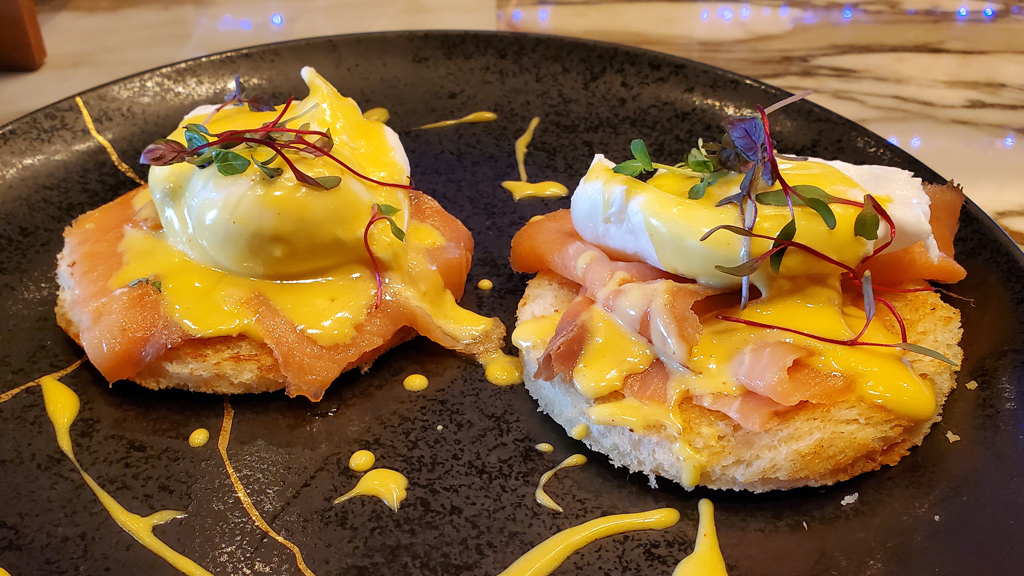
Thanks to my Marriott Ambassador Elite status, I got to enjoy a free breakfast at The Pepper Club by Todd English, the restaurant directly connected to my hotel. I decided to order the Eggs Benedict with smoked salmon because it was priced perfectly efficiently to be able to use my entire breakfast credit.

Maybe it’s because I’m just used to staying at lower-end hotels for the bargain and convenience, but the Eggs Benedict was unexpectedly delicious. It tasted like an actual high-end breakfast restaurant dish—everything was cooked well, the presentation was nice, and the flavors had just the right amount of intensity. I’m also usually not the biggest fan of cheese, but the cheese sauce was just that—more of a sauce than actual cheese—so it didn’t have any of the moldy or vomit-ey smell that I prefer to avoid.
While in town in Las Vegas, I also met up with one of my friends and went to 138 Restaurant in Henderson, a restaurant that specializes in dry-aged food.

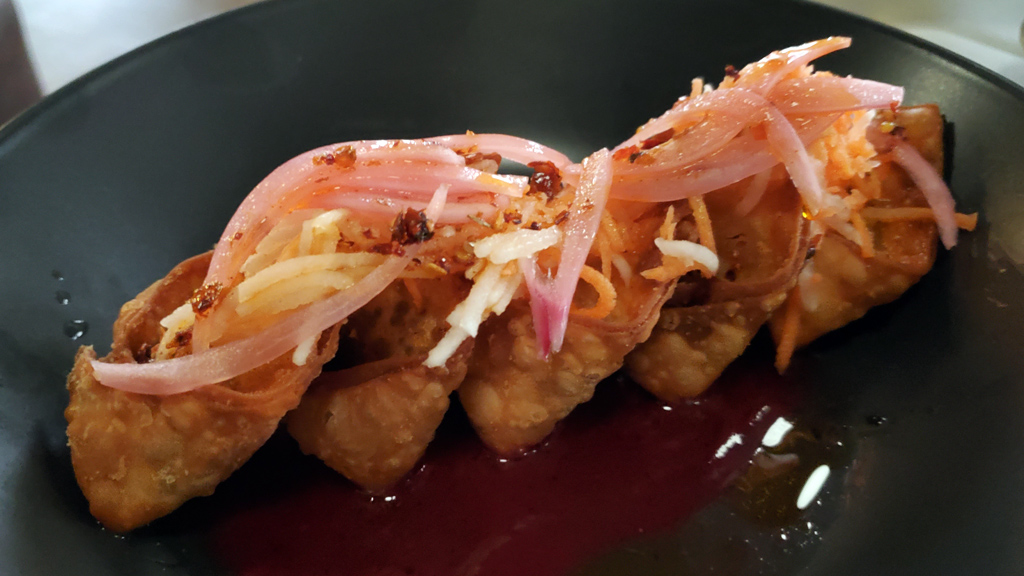
For my appetizer, I ordered duck confit wontons with chili oil, fried garlic, and sweet and sour sauce. I wasn’t a big fan of it—the pickled vegetables on top were way too sour, the sauce was overwhelming, and the wontons were over-fried, so I could barely even tell that there was any duck inside at all.
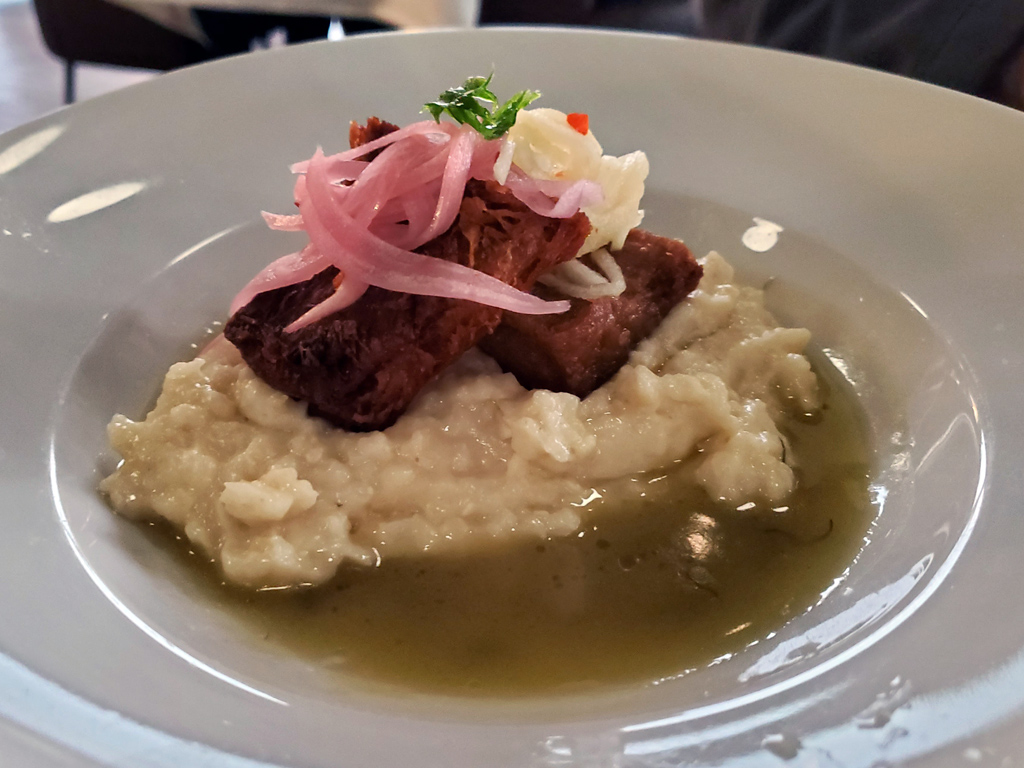
My friend ordered dry aged crispy pork belly with fennel butter, pickled shallots, apple, and pork jus.
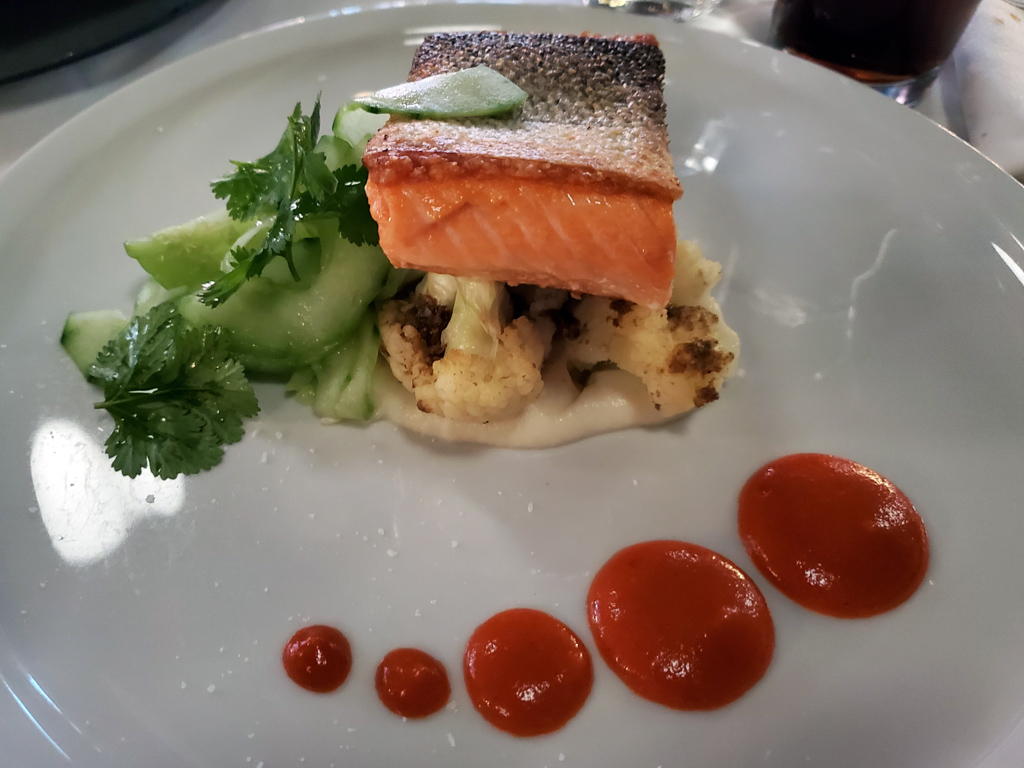
For my main dish, I got Ōra King salmon with aloo gobi spiced cauliflower, red pepper coulis, cucumber, and cilantro, with a special request for it to be cooked less salty. I liked this much better than my appetizer—the flavors were much more complementary, and I could actually tell what the meat was that I was eating.

Although the menu didn’t clarify, the waitress said that the salmon had been dry aged. I couldn’t really tell, and it just tasted like I was pretty much just eating very normal salmon.
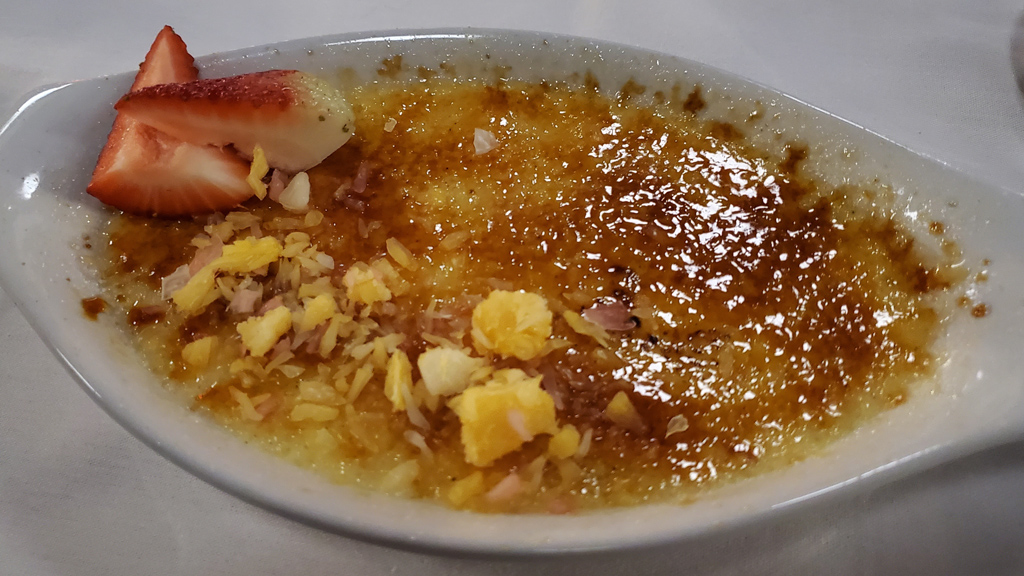
Finally, for dessert, I got some crème brûlée. I realized after-the-fact that the photograph makes it look small, but it was actually literally about double the portion size that I would expect from an already big portion. It tasted amazing, though I’m pretty sure I ate a week’s worth of sugar intake in just that one bowl.
🕵️
 

—§—


Investment allocation breakdown for 2023 Q1

Disclaimer: I am not a registered investment advisor, and even if I was, I wouldn’t be your investment advisor. The information found in this blog post is in­tended to be strictly anecdotal and should not be construed as financial advice. Everyone’s situation is uniquely different, so if you are seeking guid­ance, be sure to consult a licensed and certified professional.

 
Another quarter, another investment allocation breakdown.

It’s almost time for me to do another comprehensive edition of one of these, similar to the one I did in July 2022, but until then, I recommend taking a look at that one to understand the finer details of why I invest the way that I do (though keeping in mind that some of that information may have al­read­y become outdated in the last three quarters).

Cash

As is expected for the first quarter of the year, my cash balance has dropped substantially from saving up during Q4 of last year in or­der to dump a lot of money into tax-advantaged accounts on the first of the year after contribution limits reset.

Because of rising rates and the fact that I use an online savings account, I’ve been able to get a passable amount of interest just from keeping cash in my bank, but I don’t want to fall into the trap of becoming comfortable with guaranteed interest and missing out on potential stock market spikes, so I made sure to move forward with my standard investment strategy without being affected by emotion-based reconsiderations or doubts.

  1.21%

Domestic broad market index funds

While the economy wasn’t doing well, I focused more on investing in high-yield dividend funds so I could continue staying in the mar­ket but not be so harshly affected by falling market prices. It’s obviously not possible to predict the future, but it seems like things might have stabilized now. As a result, I’m holding all the high-yield dividend funds that I bought already, but all my new money is go­ing into the total stock market instead.

 42.35%

International total market index funds

No changes.

  4.22%

Target date funds

Like I do every year on January 1 after the annual contribution limit reset, I contributed the maximum amounts allowed to my Roth IRA and Health Savings Account (HSA) and put several thousand dollars into my SEP-IRA (if you’re not familiar, the SEP-IRA con­tri­bu­tion limit is dynamic based on your net earnings, so I never know what exactly my limit is going to be until the year’s Sched­ule C is complete).

I self-manage and self-allocate all my non-retirement savings, but for savings in retirement accounts, I use target-date funds that will au­to­mat­i­cal­ly reallocate my money into safer investment products as I get older.

 19.52%

Real estate investment trusts (REITs)

No changes.

 12.36%

Bonds

My allocation in bonds went up by a little bit since last quarter because of the purchase limit reset on Series I bonds with the United States Treasury. I don’t plan on this being a long-term thing, but at least for now when inflation is still high, Series I bonds are still a high­er guaranteed rate of return than certificates of deposit, even with the higher interest rates nowadays.

  7.40%

Cryptocurrency

I know I said I wouldn’t buy more cryptocurrency and just hold onto what I bought years ago and wait it out, but after the recent col­lapse of Silicon Valley Bank and the unprecedented move by the FDIC to insure all customer deposits (as opposed to just up to $250k) made me lose a little bit more faith in the United States dollar.

I was clearly not alone, because the price of Bitcoin started steadily climbing. It didn’t go up nowhere near enough for me to be able to recover my previous losses in cryptocurrency, but because I bought in shortly after the SVB incident at a lower price, my recent earn­ings from the past few weeks have offset some of my previous losses.

  5.50%

Individual stocks and private companies

If you remember from my previous financial breakdowns, I generally only invest in companies that I believe in and personally use fre­quent­ly. There is one more company I added this past quarter, which I will probably disclose the next time I do a “comprehensive e­di­tion” version of one of these breakdowns.

On somewhat of a related note, a company in which I invested during a private equity funding round a while back just completed its in­i­tial public offering. The stock price spiked up very hard… then plummeted uncontrollably. My original investment is now less than a tenth of what it used to be. 🤦 That should serve as a warning of the danger of investing in individual companies.

  5.23%

Precious metals

I don’t know if this is because of the substantially higher amount of money I have in Vanguard compared to Fidelity, but in Vanguard, I’m able to make purchases first and go into a negative settlement fund balance—almost as if I am investing on margin—but incur no interest or fees as long as I make my account whole via a direct deposit by the settlement date. Unfortunately, Fidelity doesn’t offer me this perk.

Because of this, every time I want to make a purchase on Fidelity, I have to pre-deposit a certain amount of money from my bank ac­count first, and then can only use that amount of money to make purchases.

This means that, on Vanguard, I can pick out my investments first, and then transfer over an exact amount of money to the cent from my savings account. However, on Fidelity, I have to estimate the approximate cost of the stocks I want to purchase, deposit a little bit more than that (in case the price goes up while I’m transacting), and then have a bit of leftover money in my settlement fund.

When I’m investing in high-risk assets like individual companies and cryptocurrency-tied securities, I have a set number of non-fractional shares that I want to purchase. With my leftover money, I’ve gotten into the habit of just putting it into more gold, which (along with the fact that the price of gold as gone a little bit up) explains why my precious metals allocation is a tiny bit higher than it was last quarter.

  1.08%

Fine art, and other collectibles

No changes.

  1.13%

If you’re used to coming to these investment allocation breakdowns to check in on my stock investment challenge with Doug Wreden, the one-year in­vesting period has concluded—you can find an in-depth analysis of the results at “One-year update: Investing US$10k in the stock market – Parkzer vs. DougDoug & Twitch Chat.”


—§—


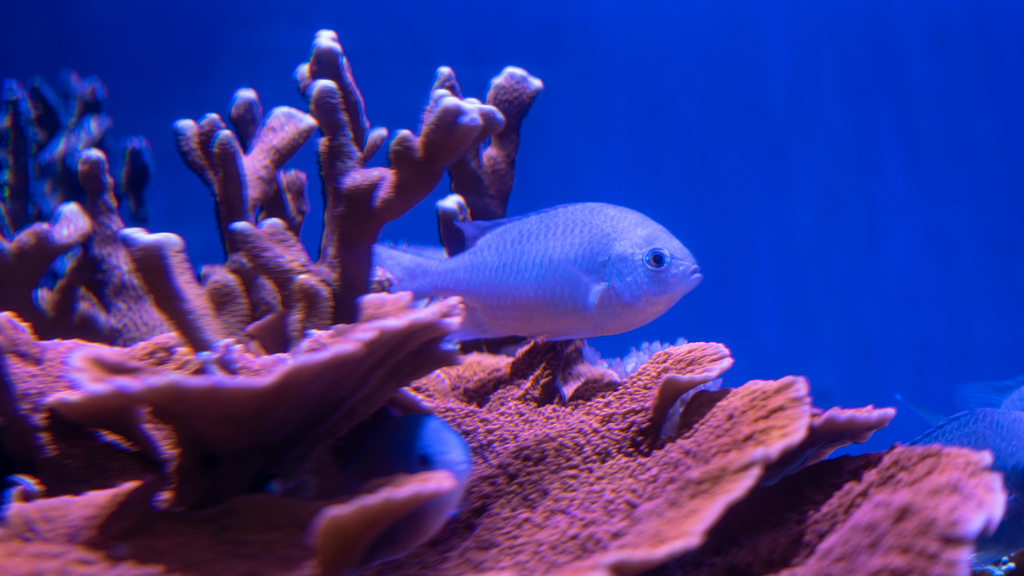
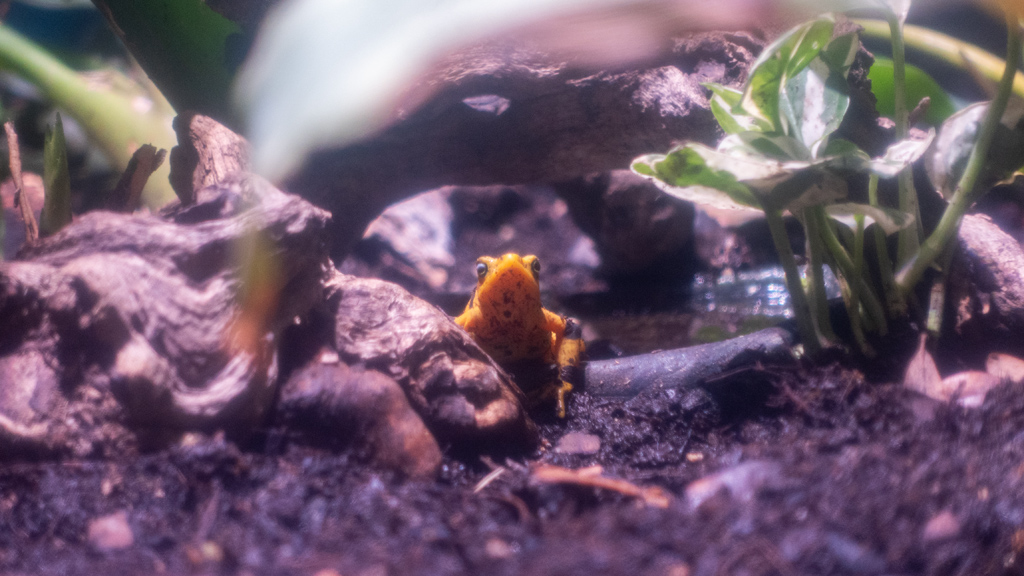
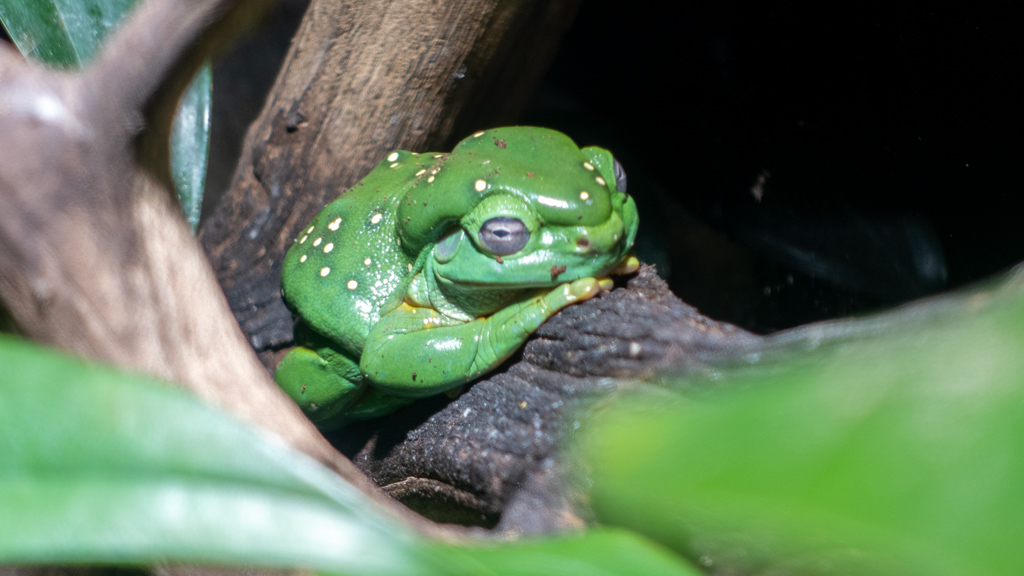
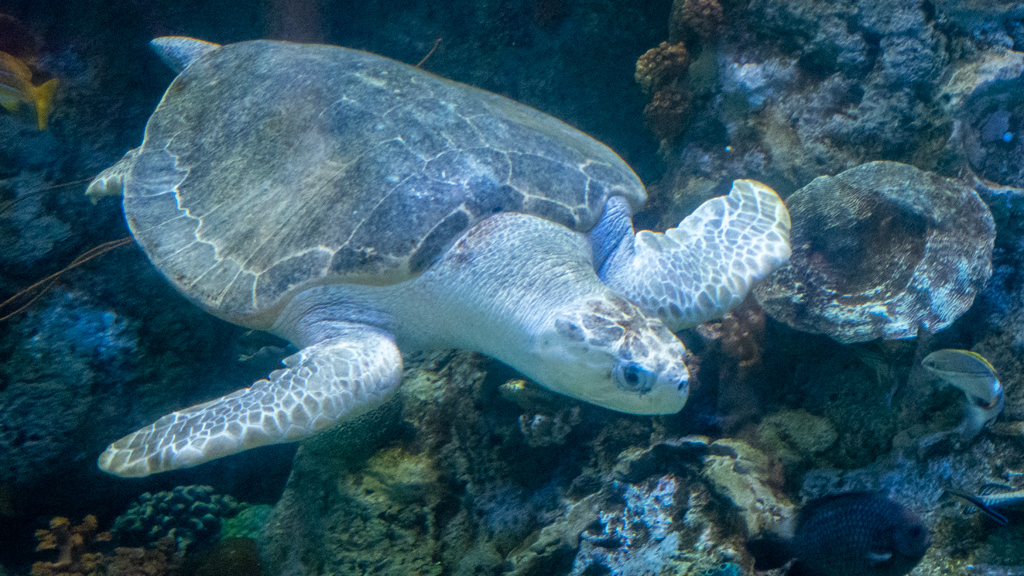
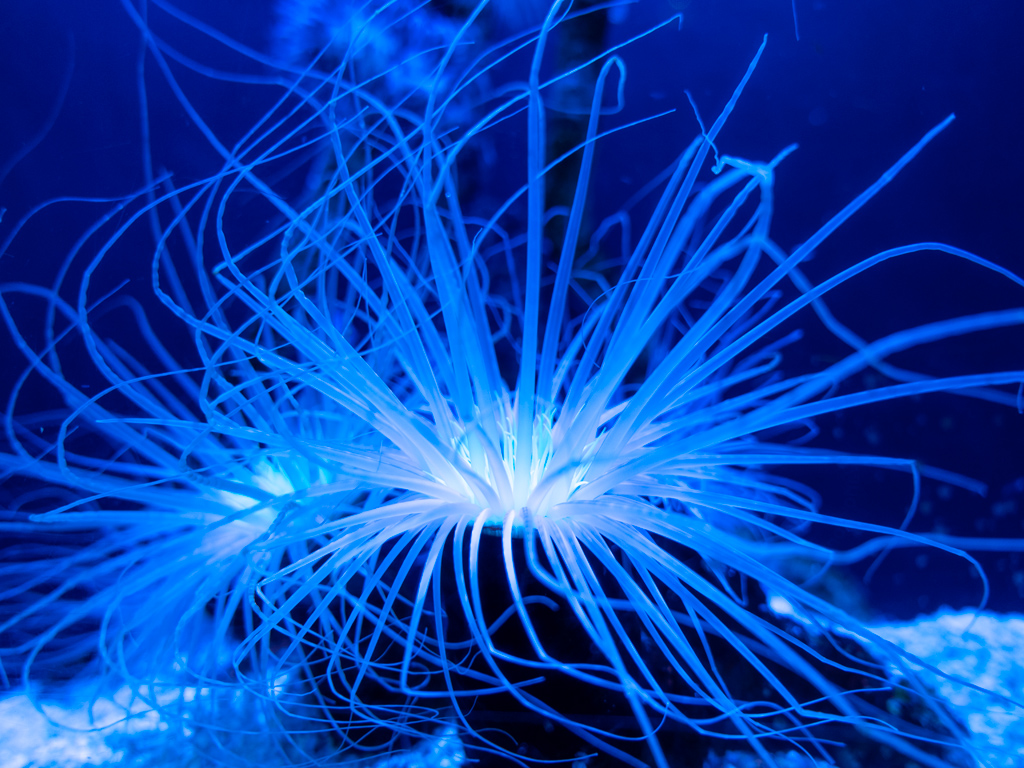
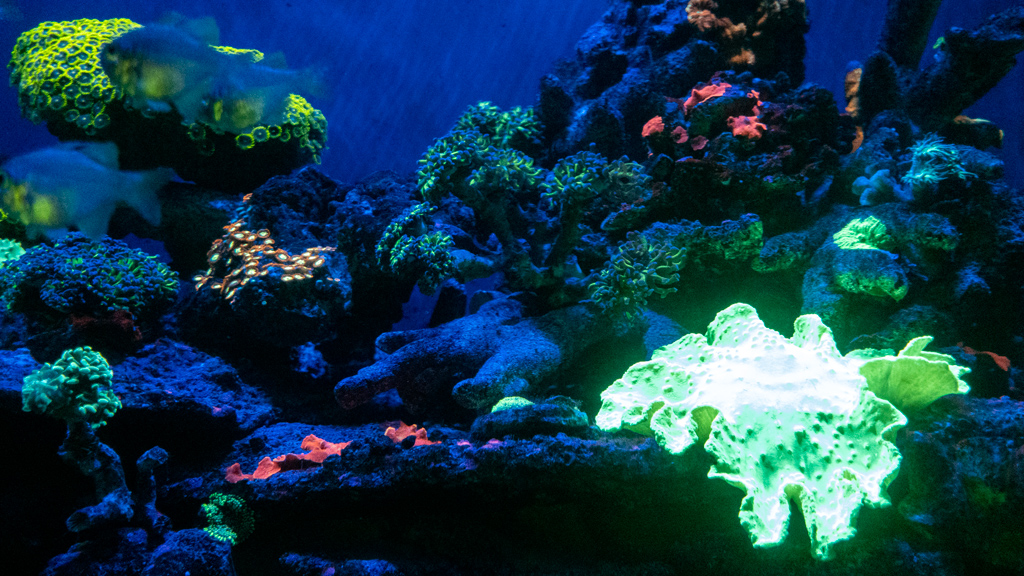
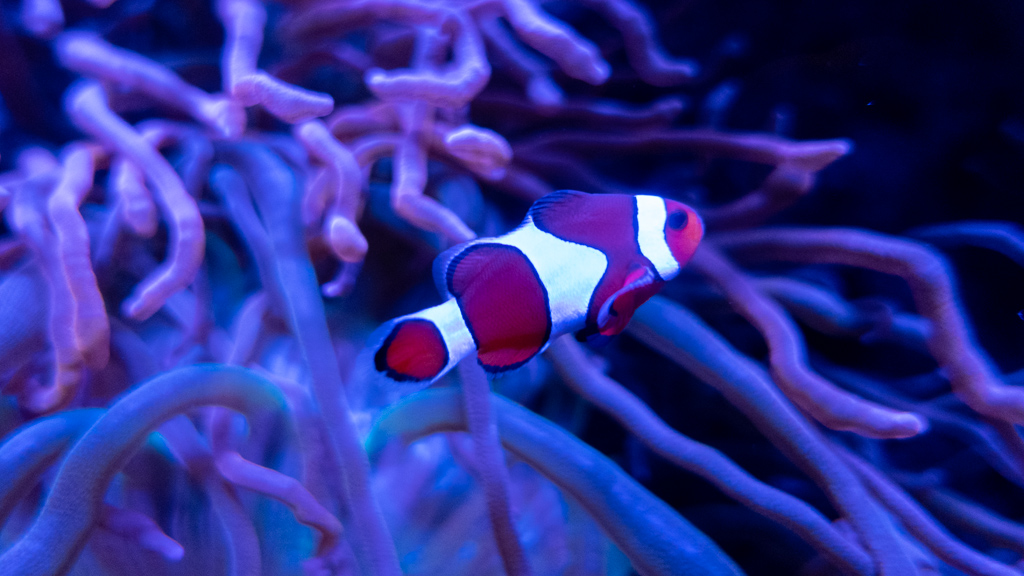
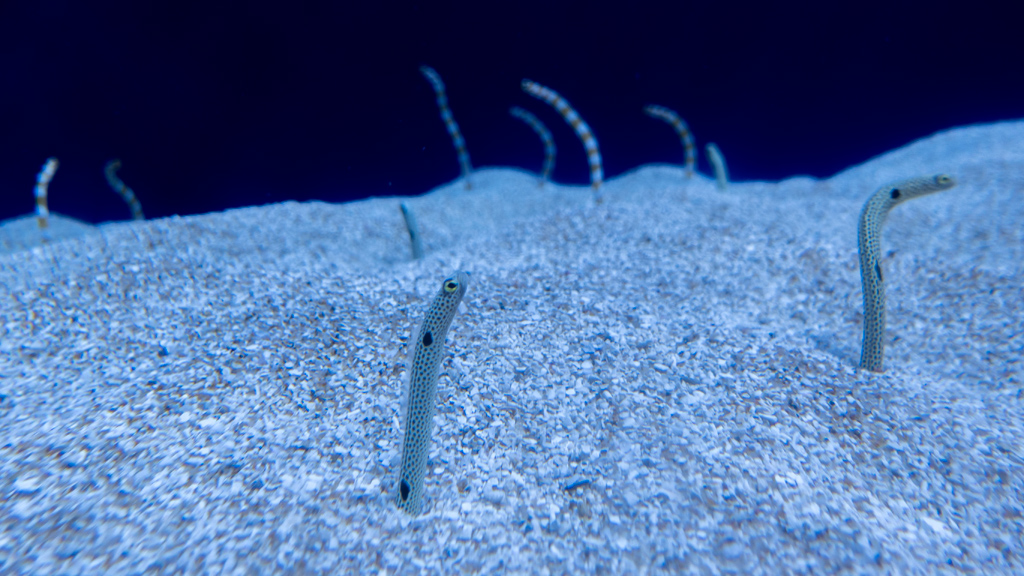
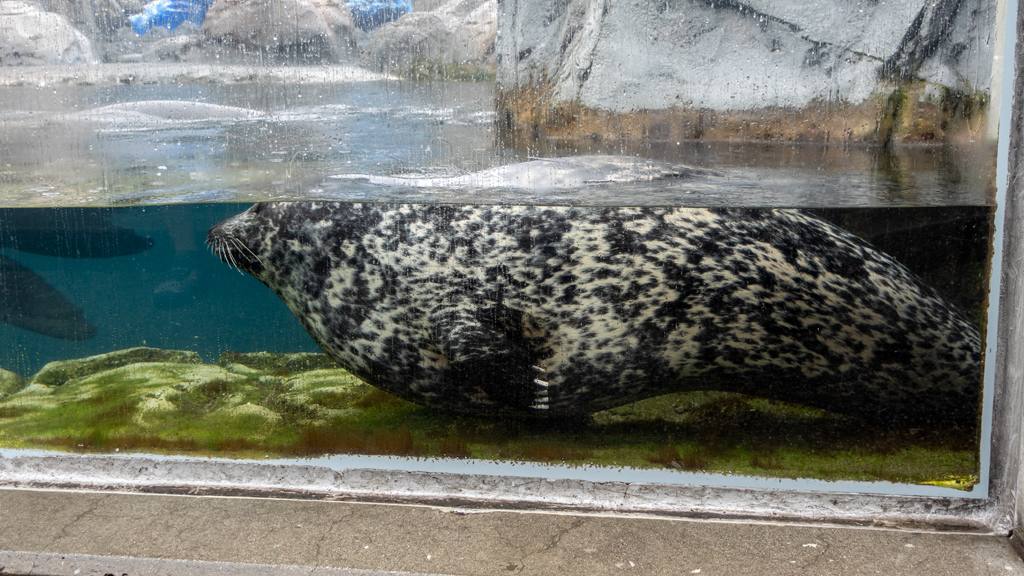
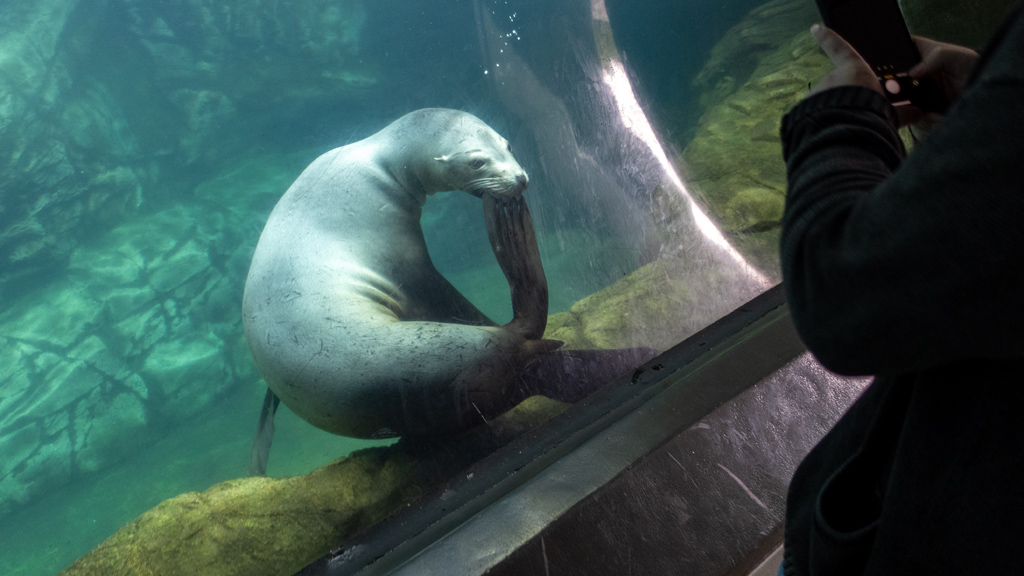
Hello, Aquarium of the Pacific in Long Beach, California

If you remember from last year, I generally only spend the winters at the Tempo headquarters in Long Beach, California while I wait out the inclement weather in other areas of the country. It’s nearing spring already, so it’s about time for me to set off; while I’m still in town, my friend David (who you might remember from previous blog posts as the greyhound rescue owner) wanted to take me to the Aquarium of the Pacific.

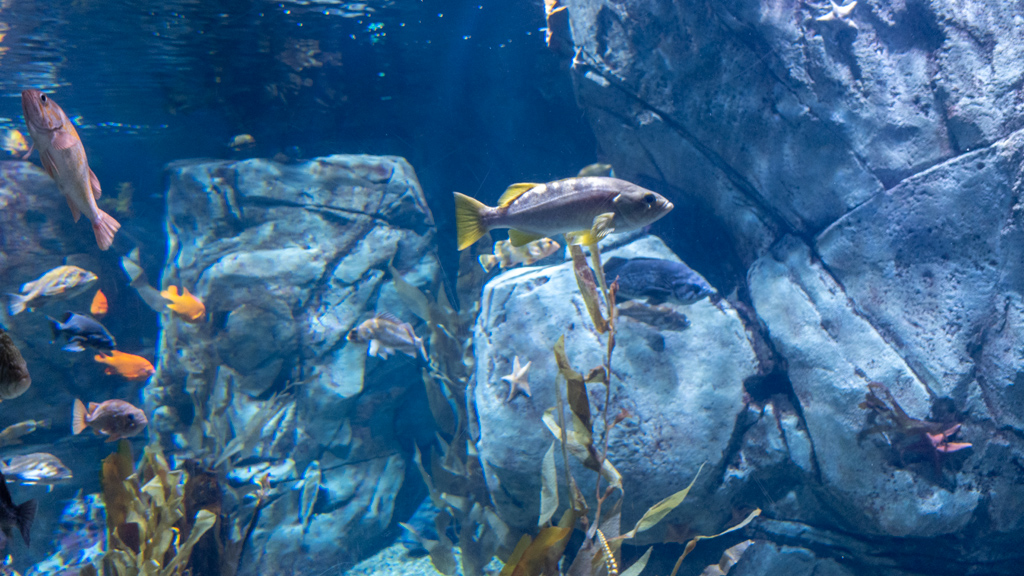
It was a nice aquarium, though I think they let way too many people in, because it was completely crammed shoulder-to-shoulder with visitors. Many of them were children, so there was the occasional ear-piercing shriek as well. Because of this, we spent a lot more time there than we originally expected—I still wanted to get my money’s worth, so I was patient and waited for the slow-moving lines so I could take a look at everything.

Here are some photos from my visit—not necessarily my favorite ones, but the ones that turned out the best:


—§—


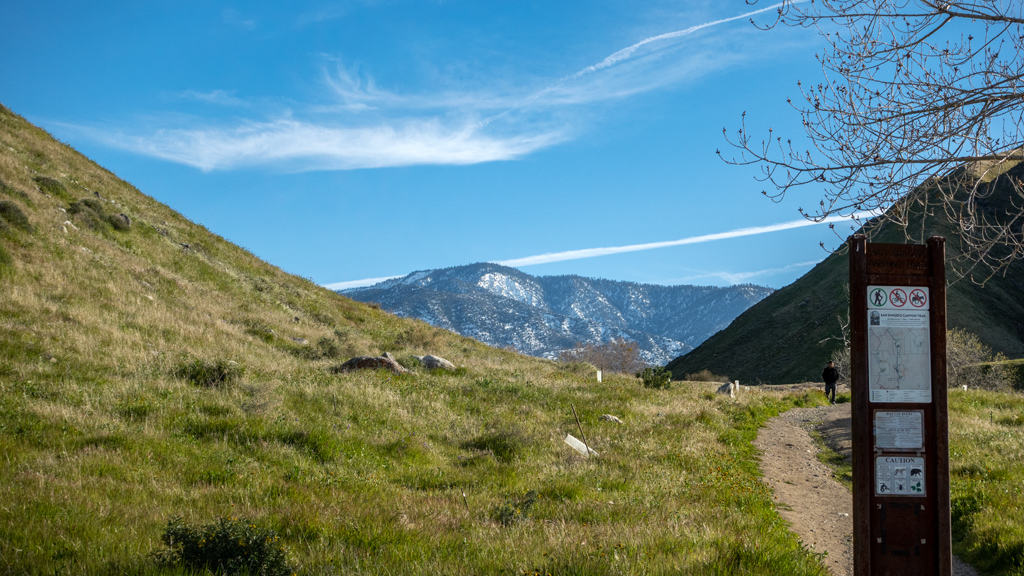
Hello, Wind Wolves Preserve in Kern County, California

There’s been an insane amount of inclement weather in California lately. It’s been raining a lot at the Tempo headquarters where I’ve temporarily set up my home base, I’ve heard that the California mountains have gotten literally several feet of snow, and I just barely missed the San Francisco Bay Area flood­ing really badly before my trip to Oakland.

The last time there was this much precipitation, there was a superbloom, which is a phenomenon where a ton of flowers bloom at the same time, es­pe­cial­ly from seeds that laid dormant for a while. In hopes of seeing one of these superblooms for myself in-person, as well as to visit a friend in the area who is planning on moving tentatively permanently to Puerto Rico, I made a quick trip an hour and a half north of Greater Los Angeles into Kern Coun­ty.

After entering the Wind Wolves Preserve, we followed some signs and drove over to the Crossing Campground and went on a short hike.

This campground had an unusually fancy bathroom.

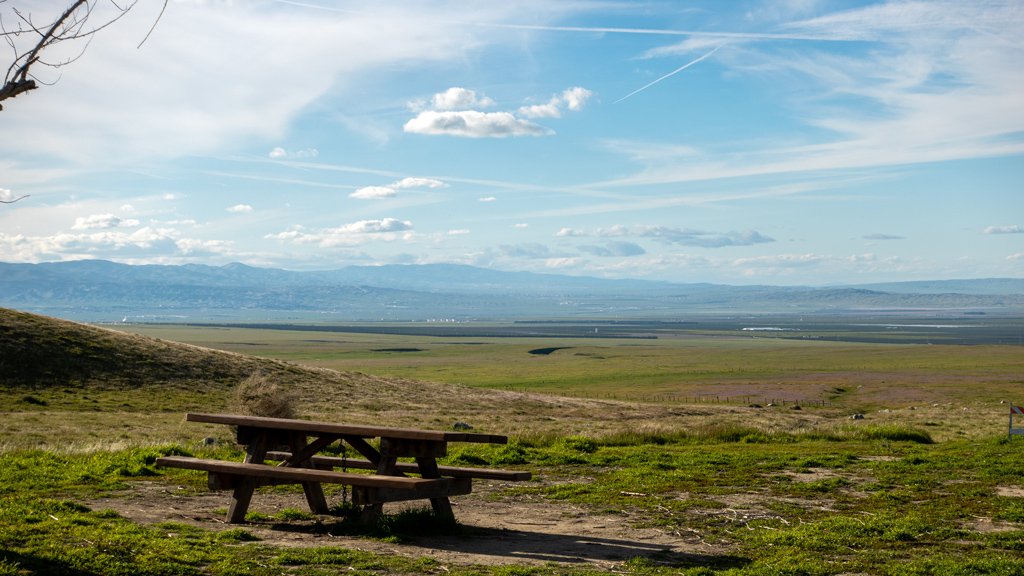
We got to the end of the trail, where we got a nice view of Bakersfield to the north.

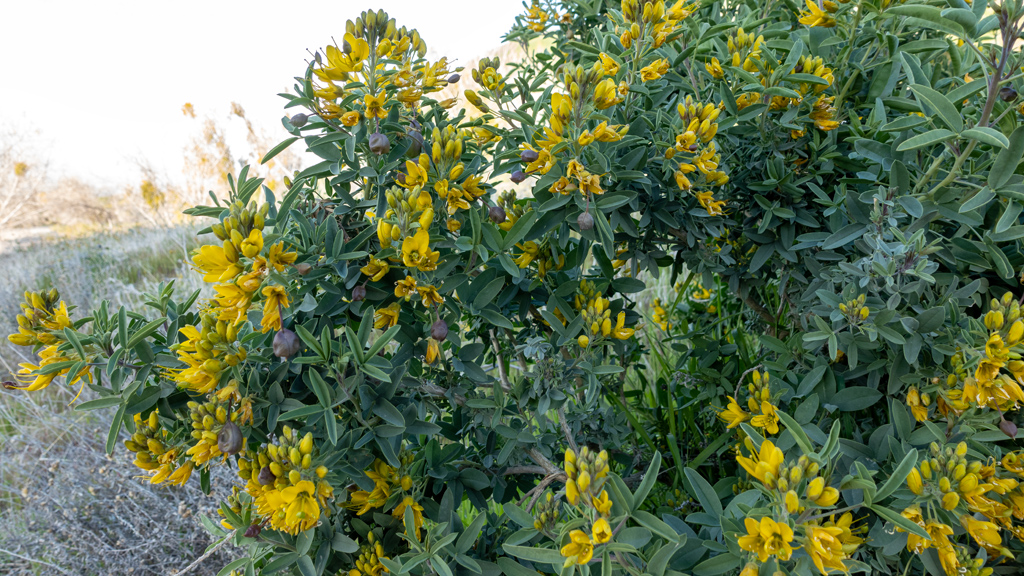
In this area of the preserve, we did see some open fields, but they weren’t covered with wildflowers—there were just a few flowering bushes along the sides.

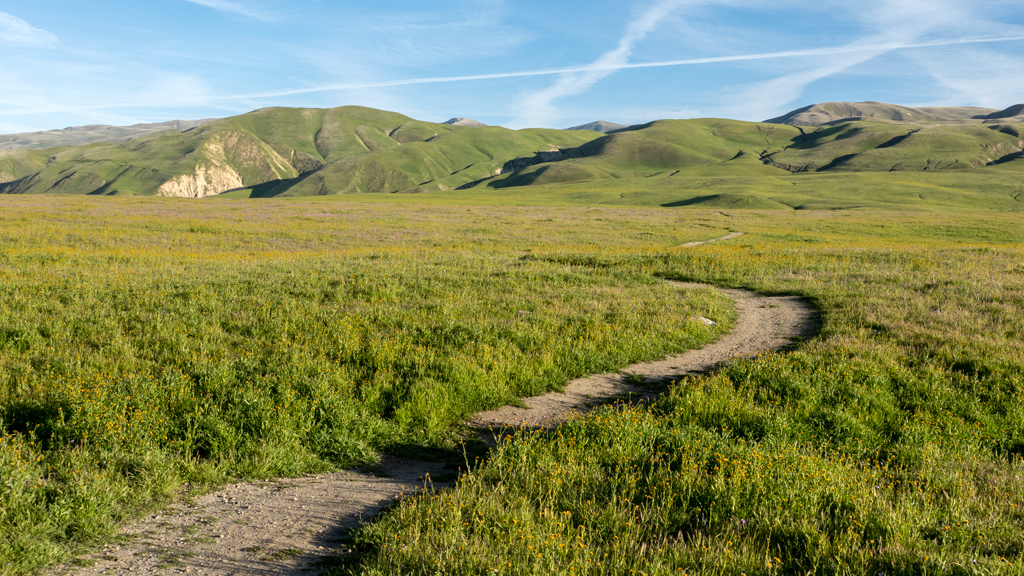
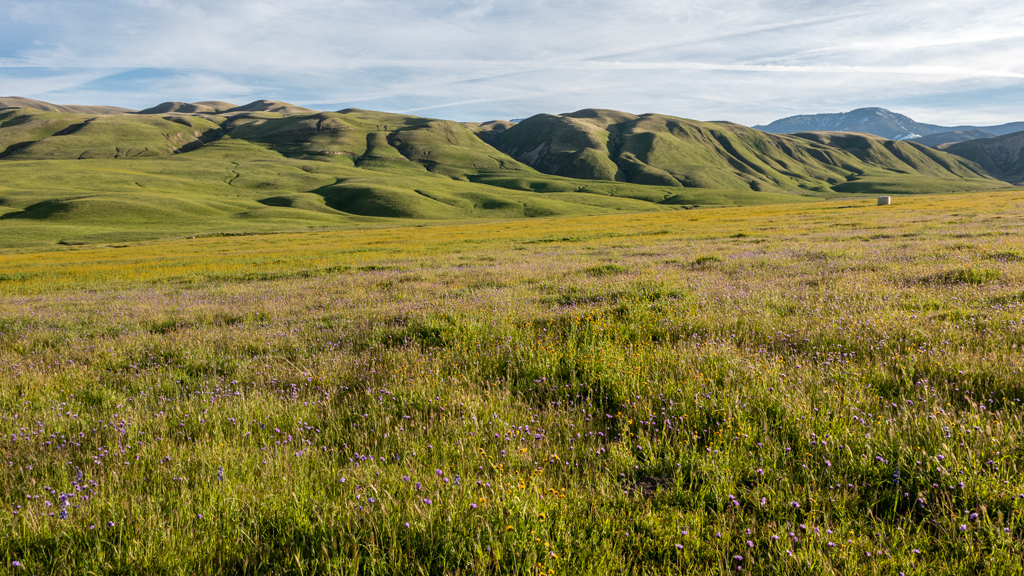
We ventured over to a different area in hopes of having better luck, which we sort of did. Unfortunately, my timing was a little bit off—it did look like there were a lot of flowers blossoming out in the fields, but they weren’t quite at full size. According to Google Maps, this area is usually pretty barren, so I guess it is good news that there was even a lush field of grass at all, let alone any flowers.

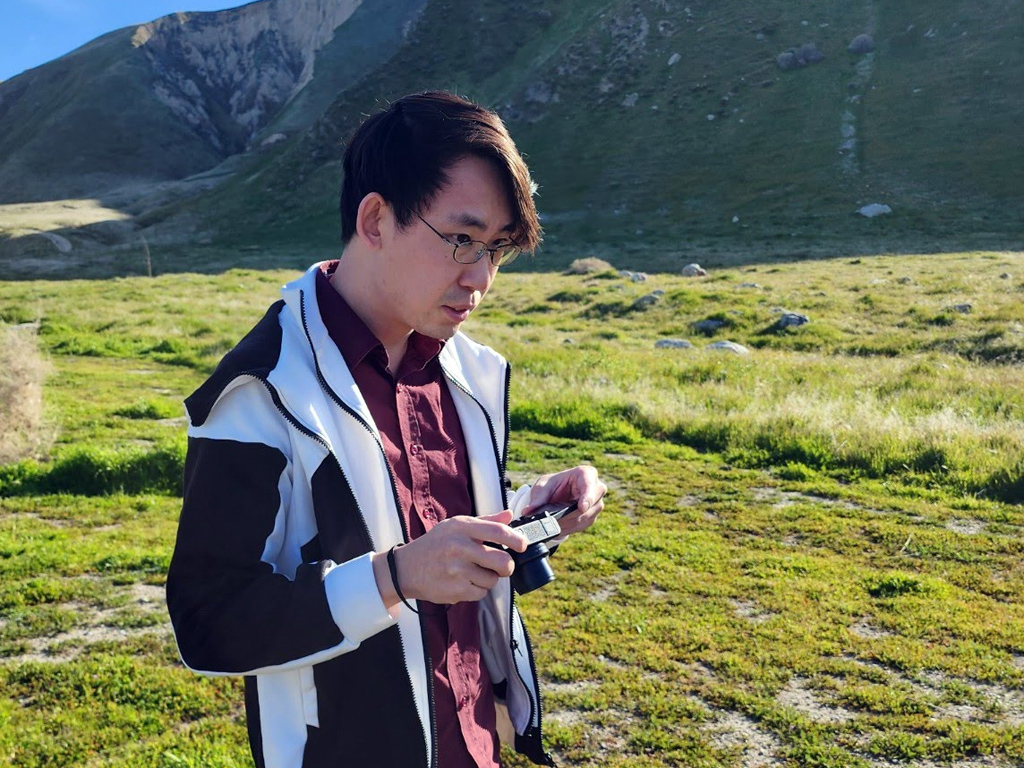
Although rare, one of the perks of doing things together with a friend is that I get to post pictures of myself too, rather than just photos exclusively of things around me.

Adam Parkzer holding a camera after taking a photograph

I wouldn’t say this was a particularly successful trip, but it wasn’t a complete failure either.

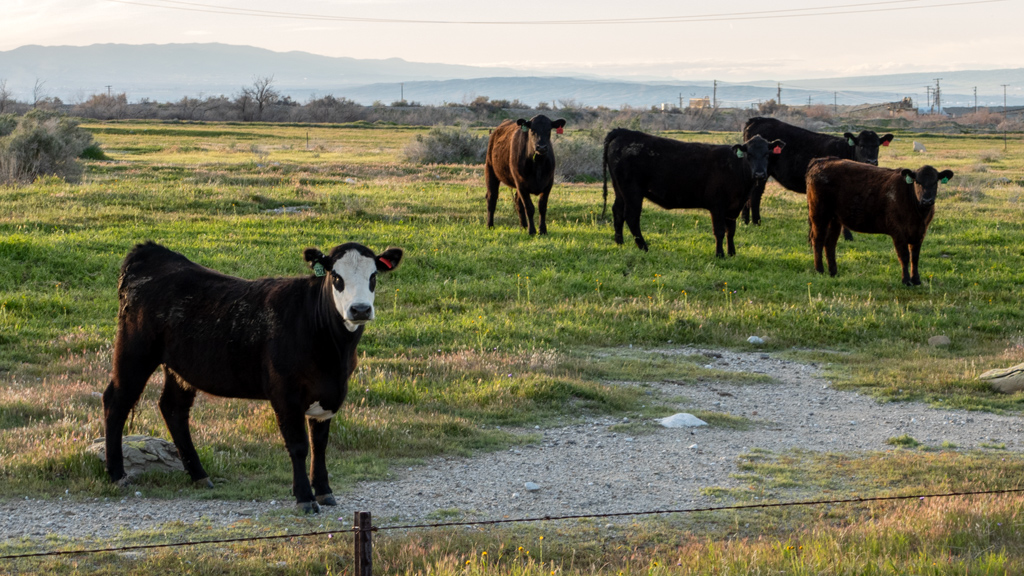
As a consolation prize, here are a bunch of cows that were ex­tremely confused why I got very excited and parked my truck on the side of the road to take a picture of them.


—§—


How I keep my assets safe from bank and brokerage insolvency

I have gotten a lot of messages today—far more than I expected, from both friends and co-workers—regarding today’s breaking news of Silicon Valley Bank’s insolvency. If you’re not familiar with what happened, an oversimplified summary is that Silicon Valley Bank overleveraged their assets and were un­able to fulfill customer withdrawals, creating a feedback loop of panic and further withdrawals, resulting in the California Department of Fi­nan­cial Pro­tec­tion and Innovation shutting down the bank and the Federal Deposit Insurance Corporation taking over operations.

Before I get into things, I want to point out that neither I nor any of my companies were affected by Silicon Valley Bank’s collapse. Neither I nor any en­ti­ty over which I have financial oversight had a Silicon Valley Bank account, and no funds were lost or locked as a result. However, it is devastating to hear that many tech startups had their entire treasuries in Silicon Valley Bank and lost everything. What is even more concerning is that Silicon Valley Bank had an extremely high percentage of customer deposits—allegedly over 95%—that were not covered under FDIC insurance.

In short, FDIC insurance protects up to US$250,000.00 in deposits per insured bank, per owner, per account category. As you can imagine, tech startups with venture capital funding likely have far more than $250k in funds that they hold in their bank, which means everything over $250k was not insured.

With that being said, there are a lot of well-written resources available online that can explain FDIC insurance, as well as the similarly-purposed Se­cu­ri­ties Investor Protection Corporation (SIPC) insurance. I recommend conducting your own research before continuing so you can have a background ba­sis upon which to analyze my post. The purpose of my blog post is to provide an example and explanation of how I apply this information to my per­son­al financial situation.

As a disclaimer, I am not a registered financial advisor, and even if I was, I would not be your advisor. This information is being provided strictly as an anecdote to provide insight into my life, and it does not imply that you should blindly copy my strategy. If you have any questions or need guidance with your own financial situation, make sure you consult a certified professional.


  1. This is less of an actionable step and more of a way of thinking, but I believe that stuff is better than money. Money is nothing more than some fancy cotton paper, metal coins, or a number on a digital screen. “Stuff” is everything else—things you can use to live your day-to-day life. You can’t eat money, but you can eat food. You can’t ride money, but you can ride a bike. You can’t live in money, but you can live in a house.

    Obviously, I do not waste my money recklessly, and I am careful to ensure I do not overspend on depreciating assets (like cars). However, because I have enough of a savings buffer, if I ever encounter a situation where I can either (1) purchase an item that will be very useful in my life in many cir­cumstances and will generally retain its value, or (2) save even more money, then I will usually err on the side of making the purchase.

    The best example of this is real estate. Although I personally do not own a physical property at this time, I always keep an eye out for good deals and closely monitor real estate trends. If the biggest banks unexpectedly fail or the value of the dollar goes to zero, there isn’t much that can give you more peace of mind than owning your own house and having guaranteed shelter.

    Just make sure you appropriately consider property insurance coverage from a private carrier, if applicable.

  2. I keep most of my assets in… well, assets. As long as you are not just holding your money at your brokerage in cash, and are instead actually pur­chas­ing stocks, securities, and funds, then your SIPC insurance coverage is US$500,000.00 per owner, per account category. For the sake of not need­less­ly compromising financial structural information about my companies, I am going to just focus on my individual self in this blog post, but keep in mind that if you own companies, each duly-formed company counts as its own separate “customer.”

    I personally hold brokerage accounts on Fidelity and Vanguard. On Fidelity, I have an individual brokerage account and Health Savings Account. On Vanguard, I have two individual brokerage accounts, a Roth IRA, a SEP-IRA, and a Traditional IRA. On Vanguard, my two individual bro­ker­age accounts count as one single account type, but all the retirement accounts count as separate account categories. As a result, with $500k in SIPC in­surance coverage for each account type at each brokerage, if I spread out my money optimally, I can get $3 million in potential coverage.

  3. I have checking and savings accounts with both Discover Bank and U.S. Bank. Although checking and savings count as one account category, the fact that I have my money spread between two separate banks means I have separate FDIC insurance coverage for both, totaling $500k across the two. I can further increase coverage by creating revocable or irrevocable trusts, as well as by creating joint accounts with other people, but for now, I only have the two basic accounts.

  4. I have brokered certificates of deposit through Vanguard. Certificates of deposit (CDs) usually aren’t the most attractive investment vehicle, but with interest rates soaring lately and the stock market’s near future still uncertain, CDs have recently become a much more reasonable option. Brokered CDs are CDs that are owned by a different financial institution but purchased through your brokerage firm.

    As you saw above, the fact that I have distributed cash between two banks increased my FDIC insurance coverage. In theory, I can open even more bank accounts for even more coverage, but at some point, it becomes a hassle to keep track of all your different bank accounts. Instead, you can purchase brokered CDs through a single account and keep everything organized on one screen with one single log-in, thus taking advantage of the offering bank’s FDIC insurance coverage without having to have a direct customer account with them.

    You can get a wide range of CDs—as short as 1 month for funds you may need soon, and usually all the way up to 5 years if you want to take ad­van­tage of the high interest rates and don’t need the money for a while. Vanguard has brokered CD options from reputable institutions like JP Mor­gan, Charles Schwab, Morgan Stanley, and Wells Fargo, just to name a few. In theory, you could use this trick to get as much FDIC insurance cov­er­age as there is banks offering CDs on your brokerage’s platform.

  5. I have been annually purchasing the maximum-allowed Series I Bonds to take advantage of their high interest rates as a result of recently-spiking inflation. Although these don’t have FDIC or SIPC insurance, they are fully backed by the United States government.

 
There are a few things to note here. First, don’t panic if you have more than the SIPC insurance limit in assets in a particular account at a particular bro­ker­age. Your assets are still your assets, and they are probably still out there somewhere. SIPC insurance only needs to kick in if your assets are actually gone due to misappropriation or other misconduct by the brokerage and cannot be recovered.

Next, at some point, solely optimizing for insurance coverage will quickly give you diminishing returns in terms of priority. For example, if you are using highly stable and reputable financial institutions and they all become insolvent with several millions of your dollars, then at that point, you probably have bigger worldly problems than worrying about the extra amount of your money that wasn’t FDIC- or SIPC-insured.

Finally, the intensity to which I have prepared for doom is a definitely on the high end. I don’t think I’ve gone so far as to reach the point of insanity by optimizing it to this degree, but you usually don’t have to worry this much about your money potentially disappearing into thin air. Make sure you don’t enter a state of paranoia by overestimating the gravity of this situation.


—§—


Hello, Gladstone and Shoreline Park in Long Beach, California

Ever since arriving in SoCal after the most recent leg of my road trip, I haven’t really been getting out to do much. I’ve gone on a few out-of-town trips since then, but while in SoCal, I’ve mostly just been staying put indoors—a stark difference from going on tourist activities, hiking, and exercising at the ho­tel gym during my travels.

When I do go out, though, it’s usually because someone invites me to do something. Prompted by one of my friends and former co-workers, I de­cid­ed to head over to the downtown Long Beach area near the convention center to make a visit to the aquarium.

Unfortunately, it seemed like there was an event going on and there was an unusually high volume of tourists in the area, so the aquarium didn’t have any walk-in tickets available, and the next open time slot wasn’t for another few hours. Instead of waiting, we de­cid­ed to stop by a restaurant and walk around the bay.

 
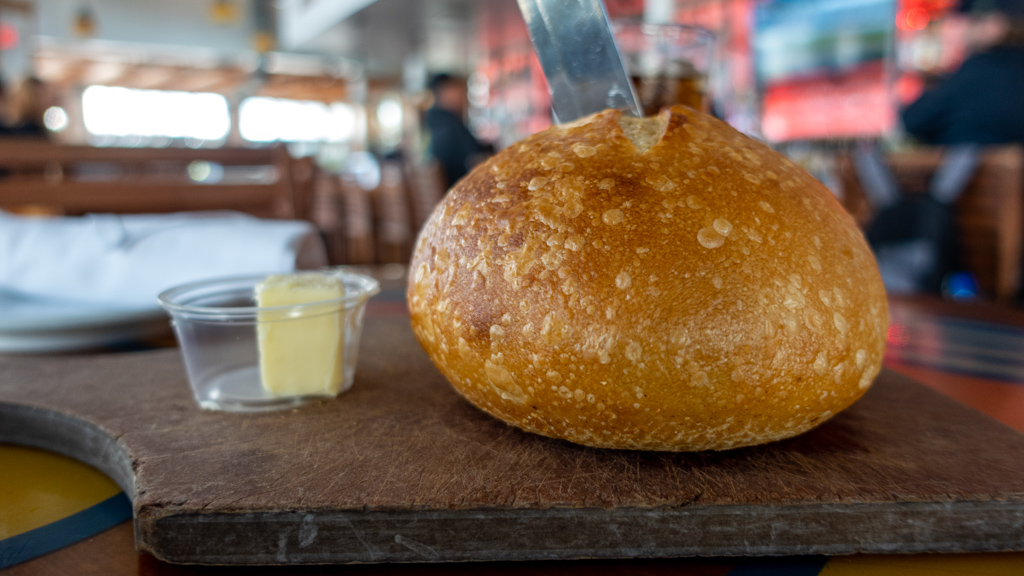
The restaurant we chose was Gladstone’s. They started us with a very large portion of free bread.

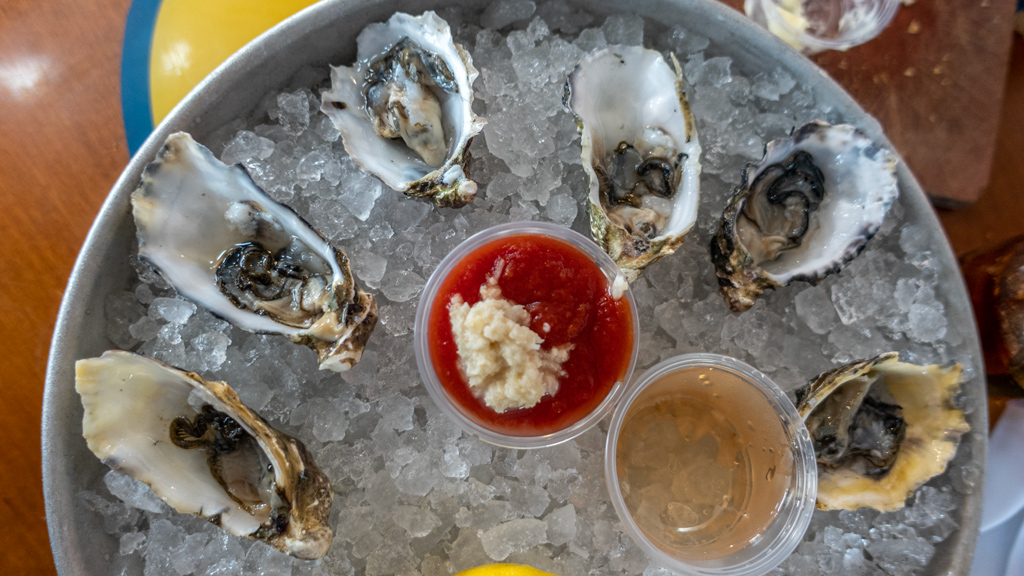
As the appetizer, I ordered a half-dozen oysters. The size of each oyster was unexpectedly small, so the portion size wasn’t very satisfying. But, at the very least, they didn’t pre-season the oysters and instead put all the sauces on the side, so I was able to eat the oysters plain and enjoy the deep, rich, un­tar­nished fla­vor of just the oysters themselves.

My friend ordered a Caesar salad with chicken breast.

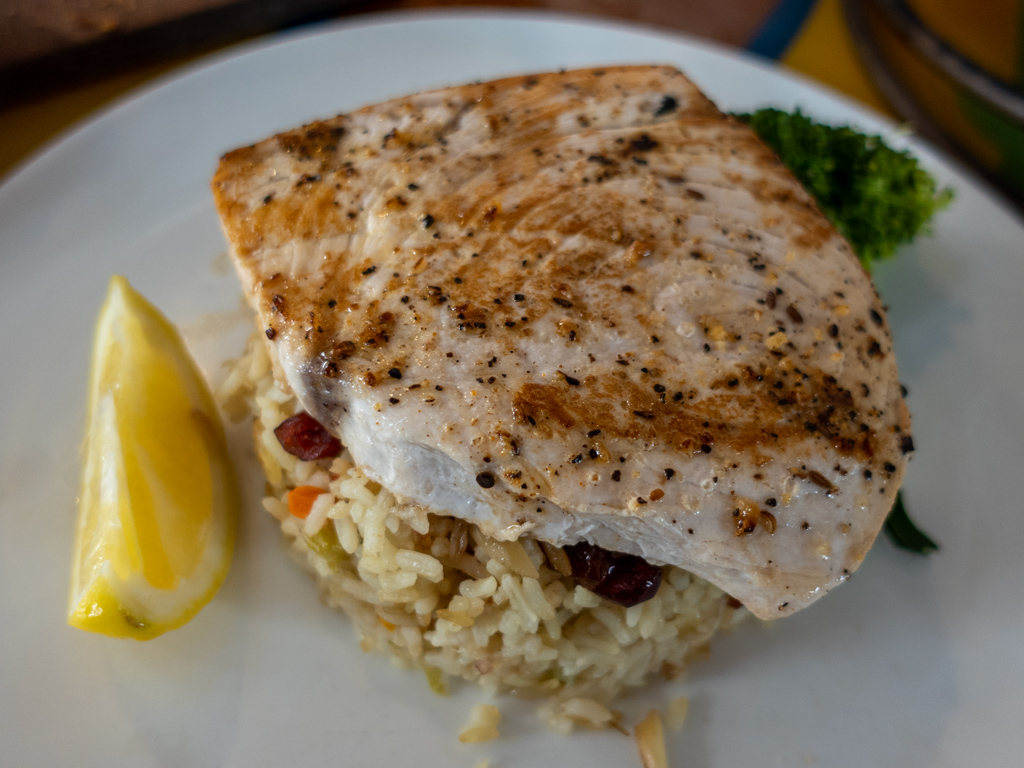
For my entrée, I selected Hawaiian swordfish.

I feel like it’s difficult to prepare swordfish in a way that makes it particularly unique, but I feel like this restaurant still did a decent job at it. The sword­fish tasted like normal swordfish, and the texture was great—it was a good mixture of firm and tender that you expect from nicely-cooked swordfish. However, the uniqueness came from the rice, which had a subtle but noticeable tang to it, which was well balanced by the slight bitterness of the broccolini.

 
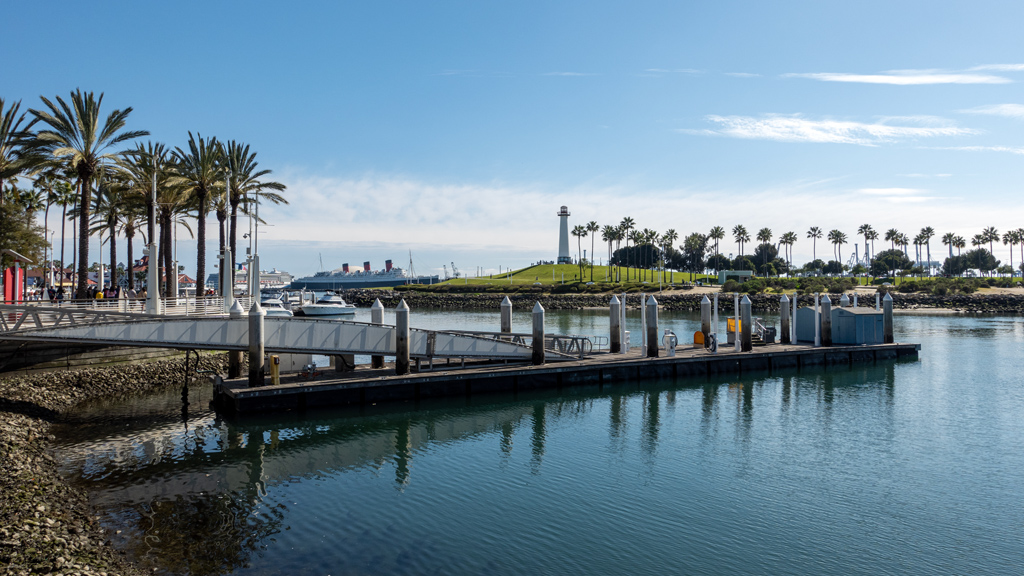
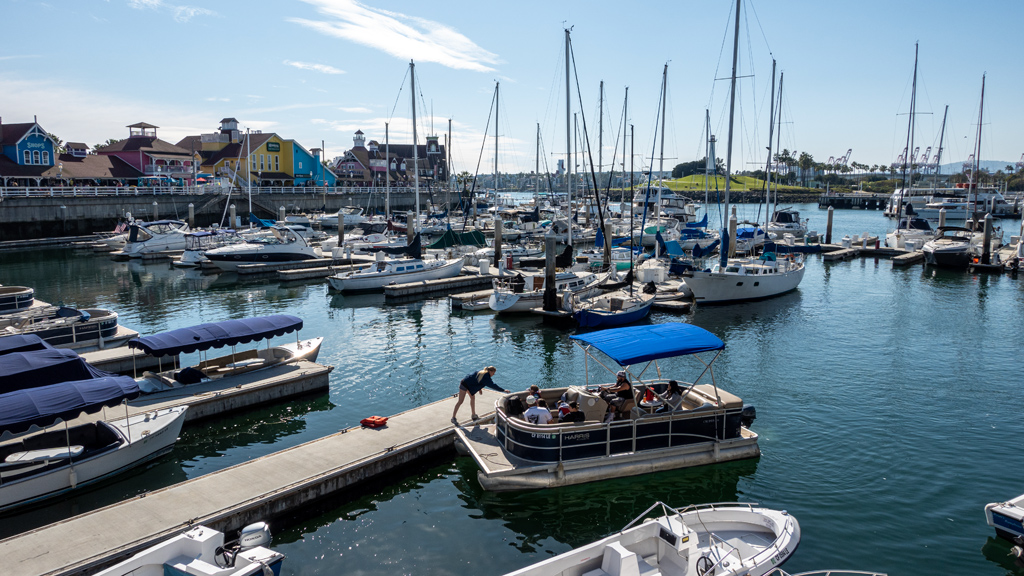
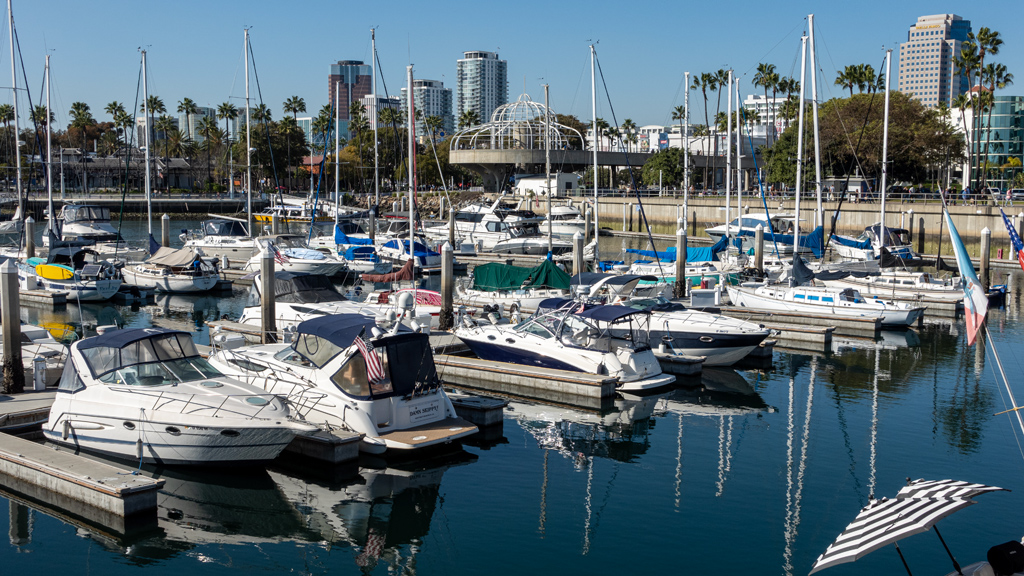
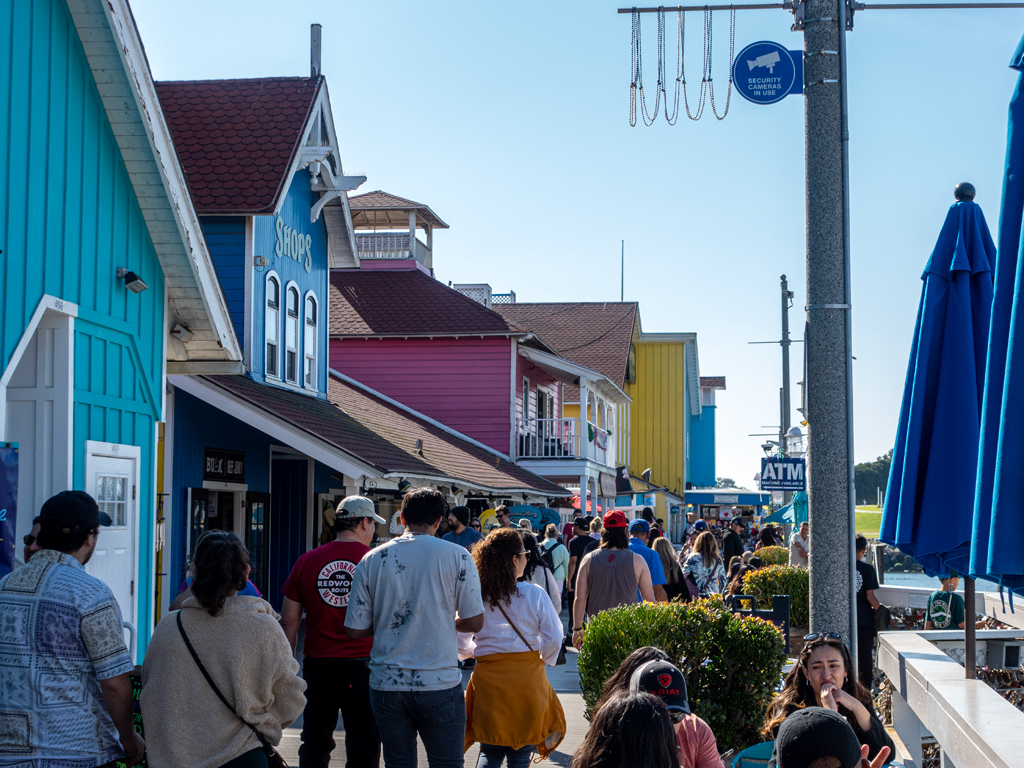
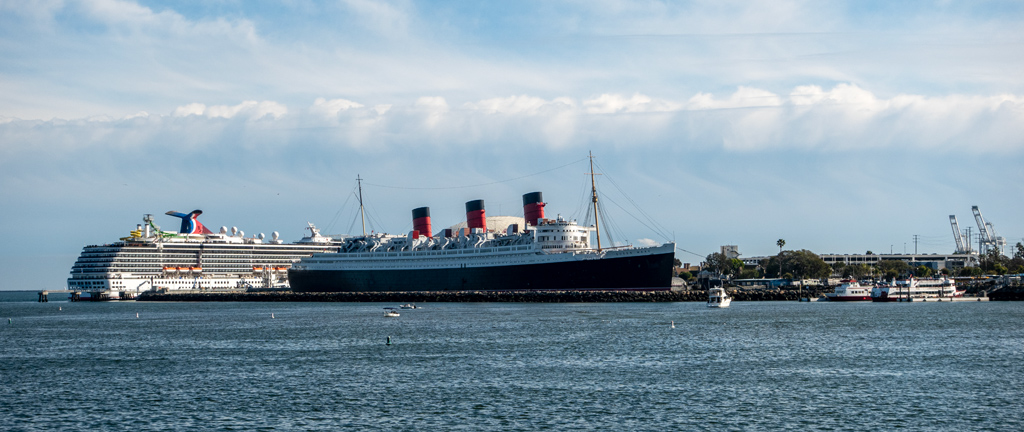
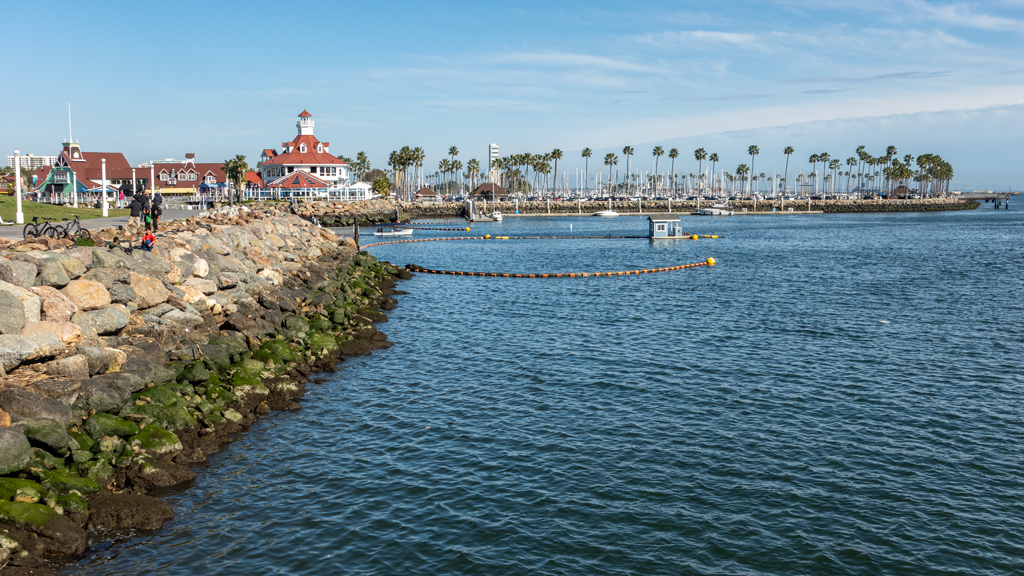
Here are some shots from Shoreline Park and the surrounding areas near the restaurant:


—§—